The American Tax System Was Built for Human Workers. What Happens When the Workers Are AI?
For more than a century, the American economy has operated on an assumption so fundamental that it is rarely questioned: economic production requires human labor.
Companies hire people. People earn wages. Employers and employees pay taxes based on those wages. Workers spend their earnings throughout the economy. Governments use tax revenue to fund Social Security, Medicare, infrastructure, defense, education, and thousands of other public functions.
Artificial intelligence could begin to challenge that structure.
The important question is no longer simply whether artificial intelligence will eliminate jobs. AI may eliminate some jobs, create others, increase worker productivity, change existing occupations, and create entirely new categories of work. The ultimate employment effect remains uncertain.
But another possibility deserves much more attention.
What happens if companies increasingly supplement human labor with AI agents capable of performing economically productive work?
Imagine a company that once required 500 employees but eventually produces considerably more output with 300 employees and hundreds or thousands of AI agents performing portions of the work previously performed by people.
Yet they may generate enormous economic value.
If that transition occurs at sufficient scale, the United States could eventually face an unusual fiscal problem: economic productivity could continue growing while an important portion of the traditional labor tax base grows much more slowly or even contracts.
That could force policymakers to ask a politically explosive question.
Should productive AI activity eventually become taxable in some form?
- AI agents do not receive salaries
- They pay no federal income taxes
- They contribute nothing to Social Security or Medicare
- Their employer pays no payroll taxes on their "labor"
- Yet they may generate enormous economic value
America's Tax System Depends Heavily on Human Labor
To understand the potential problem, consider how the federal government currently collects revenue.
In its February 2024 baseline, the Congressional Budget Office projected approximately $2.8 trillion in individual income taxes and $1.8 trillion in payroll taxes for fiscal year 2026. Corporate income taxes, by comparison, are projected at approximately $404 billion. In other words, taxes closely connected to individuals and employment represent an enormous component of federal revenue. These figures are historical projections for 2026, not actual receipts or a current baseline.
Payroll taxation illustrates the relationship particularly clearly.
In 2026, employees generally pay 6.2 percent of covered wages toward Social Security and 1.45 percent toward Medicare. Employers generally contribute another 6.2 percent and 1.45 percent respectively. The Social Security portion applies up to the 2026 taxable wage maximum of $184,500, while Medicare taxation generally has no comparable wage ceiling.
Therefore, for many employees, 15.3 percent of wages effectively flows into Social Security and Medicare when the employer and employee portions are combined.
Consider a simplified example.
Now imagine that technological change eventually allows the company to operate with 600 employees while AI systems perform a significant portion of the work formerly performed by the other 400.
The company could become more productive and profitable.
But $32 million of annual human payroll would have disappeared from our simplified example.
So would much of the payroll-tax activity associated with those wages.
This is where AI becomes more than a labor issue.
It becomes a tax-base issue.
- 1,000 workers × $80,000 average salary = $80 million in payroll
- Combined 15.3% payroll tax ≈ $12.24 million to Social Security and Medicare
- After automation: 600 employees, $32 million of payroll gone
- Most of the payroll-tax activity on those wages disappears with them
A tax base closely connected to people
Selected FY2026 revenue projections · trillions of dollars
How payroll tax splits between worker and employer
2026 rates · Social Security and Medicare combined
| Component | Employee pays | Employer pays | Wage limit |
|---|---|---|---|
| Social Security (OASDI) | 6.2% | 6.2% | First $184,500 of wages |
| Medicare (HI) | 1.45% | 1.45% | No limit |
| Combined | 7.65% | 7.65% | 15.3% of covered wages |
- 01InventoryIdentify systems and their owners
- 02OversightDocument autonomy and human review
- 03ActivityUnderstand costs and business functions
- 04ReviewEvaluate economic and policy implications
The Agentic AI Economy Changes the Equation
Traditional automation already created versions of this question. A factory might replace manual processes with robotics, for example.
Agentic AI could make the issue much broader because AI is moving automation into areas of the economy traditionally associated with cognitive labor.
An AI agent can potentially research prospects, analyze documents, prepare reports, generate code, answer customer questions, conduct preliminary financial analysis, schedule meetings, monitor systems, draft marketing campaigns, qualify sales opportunities, review contracts, perform administrative work, and coordinate with other AI agents.
Instead of automation primarily affecting physical production, AI can potentially supplement portions of the work performed in offices across virtually every industry.
OECD research examines how AI is shaping labor markets and how governments can respond through employment, skills and social-policy frameworks. AI-specific approaches continue to evolve.
That makes the next decade particularly important.
We may be moving from a tool-assisted workflow toward an agentic one.
The human does not necessarily disappear. Instead, one employee may supervise a collection of digital workers.
That is augmentation rather than complete replacement, but from a taxation perspective the distinction may eventually become complicated.
Suppose ten employees assisted by AI agents can generate the economic output previously requiring twenty-five employees.
The company may still employ people, and those remaining employees may earn higher wages.
But the relationship between economic output and taxable human payroll has changed.
More economic output does not necessarily mean more taxable human payroll.
Same wage. Fewer workers. Less payroll tax.
Combined employer + employee Social Security and Medicare contributions
40% below the starting scenario
The Government Could Face a Revenue Paradox
The CBO baseline cited here did not assume a sudden AI-driven collapse of the payroll-tax system. Its projections showed payroll tax receipts at roughly 5.7 percent of GDP over the projection period.
That distinction is critical.
An AI tax crisis is not currently an established fiscal outcome. It is a scenario worth examining if AI adoption produces a much larger structural change in employment and compensation than current baseline forecasts anticipate.
Suppose, however, that during the 2030s AI productivity accelerates dramatically.
Companies produce more.
Corporate margins expand.
GDP grows.
But human labor represents a smaller percentage of the production process.
The government could encounter a paradox:
The economy becomes more productive while portions of the traditional employment-tax base become less productive as a source of government revenue.
That would put enormous pressure on Congress.
Social Security and Medicare are particularly important because payroll taxes are specifically tied to financing those programs. CBO reported approximately $1.7 trillion in payroll tax receipts in 2025.
If taxable payroll eventually becomes structurally weaker because companies require fewer human labor hours per dollar of economic output, policymakers would have several choices.
The last possibility leads directly toward the concept of an AI productivity tax.
The economy becomes more productive while the employment-tax base becomes less productive as a source of revenue.
- Raise taxes on remaining workers
- Increase employer payroll-tax rates
- Increase corporate taxation
- Expand consumption taxes
- Reduce government spending or benefits
- Increase borrowing
- Capture some of the economic value generated by automation and AI
Higher wages can offset some payroll erosion
Annual combined payroll taxes · same starting workforce of 1,000 at $80,000
even if remaining wages rise 20%
Would America Actually Tax AI Agents?
The phrase "AI agent tax" sounds futuristic, but policymakers would not literally have to declare an algorithm an employee.
Instead, Congress could create a tax mechanism based on the economic activity surrounding AI.
There are several ways this could theoretically happen.
Five ways to measure value. Five different trade-offs.
Conceptual comparison · possible policy approaches, not enacted AI taxes
Five theoretical approaches at a glance
Conceptual comparison · none of these are enacted AI-specific taxes
| Approach | What is measured | Measurability | Main weakness |
|---|---|---|---|
| Compute tax | Computing resources used | High | Compute ≠ jobs displaced |
| Usage excise tax | Metered AI service consumption | High | May discourage adoption |
| Automation adjustment | Payroll reduction + AI investment | Medium | Causation is hard to prove |
| Agent registration fees | Registered autonomous systems | Medium | Requires new reporting infrastructure |
| Tax the value, not the AI | Profits, dividends, capital gains | High | Isolating AI's contribution is difficult |
AI Compute Tax
Companies could be taxed based on certain categories or quantities of computing resources used for large-scale AI operations.
This approach has an obvious weakness. Computing activity does not necessarily correspond cleanly to labor displacement. A medical research system consuming enormous computing resources might eliminate no jobs whatsoever while producing tremendous public benefit.
AI Usage Excise Tax
The government could impose an excise tax on certain commercial AI services.
Companies might pay a small tax based on API usage, agent transactions, inference expenditure, or AI service consumption.
This would be relatively measurable because commercial AI activity frequently flows through cloud infrastructure and metered services.
But it could discourage AI adoption and push workloads toward different technical architectures merely to minimize taxes.
Automation Adjustment Tax
A more targeted approach could look at significant reductions in human payroll occurring alongside substantial investments in automation.
Imagine a company reducing annual payroll from $100 million to $60 million while spending $15 million on AI infrastructure that performs many of the displaced functions.
Tax policy could theoretically apply an adjustment intended to recover part of the lost employment-tax contribution.
That would resemble an automation tax more than an AI tax.
But determining causation would be extraordinarily difficult.
Government would need to avoid punishing ordinary technological progress.
- Did AI eliminate the jobs?
- Did the company restructure?
- Were jobs outsourced?
- Did productivity improve?
- Did customer demand decline?
AI Agent Registration and Commercial Activity Fees
Another possibility is that companies operating autonomous AI agents above certain risk or activity thresholds could eventually be required to register them.
Registration could initially exist for governance and accountability rather than taxation.
But once governments can identify commercially deployed autonomous systems, the infrastructure for fees or taxes becomes possible.
An enterprise might eventually report:
This would create an entirely new category of economic reporting.
- 2,350 active AI agents
- 17 high-impact AI systems
- 12.8 million autonomous transactions
- $38 million estimated AI-attributable economic output
Taxing AI-Generated Value Rather Than AI Itself
Perhaps the most economically coherent approach would be not to tax AI at all.
Instead, government could shift taxation toward where the financial benefits of AI ultimately appear.
If AI allows a corporation to reduce costs by $50 million and profits consequently increase by $40 million, government could capture additional revenue through corporate taxation.
If shareholders receive increased dividends or realize greater capital gains, taxation could occur there.
This approach avoids the nearly impossible question of whether an AI agent should be treated as a virtual employee.
The policy principle would instead become:
Tax the economic return generated by automation rather than pretending the machine is a person.
That distinction could become extremely important.
The Most Difficult Question: What Counts as an AI Worker?
A tax on AI agents creates a definitional nightmare.
Automation has eliminated work for decades.
Excel eliminated enormous amounts of manual accounting work. ATMs changed banking employment. Enterprise systems transformed administrative departments. Industrial robots changed manufacturing.
Why should an AI agent suddenly become taxable?
The answer cannot simply be that the technology replaces human effort.
Almost every productivity technology does that.
A workable tax framework would therefore have to distinguish between tools that increase human productivity and autonomous systems performing sustained economic functions with limited human intervention.
Even that boundary will be difficult to draw.
- Is Microsoft Copilot an AI worker?
- Is a chatbot?
- What about an AI system that writes 30% of a programmer's code?
- What about an AI sales agent that sends 100,000 personalized emails?
- What about a system that automatically reviews invoices?
The spectrum from tool to "worker"
Illustrative classification · where common systems might fall
| System | Autonomy | Human involvement | Worker-like? |
|---|---|---|---|
| Spell checker | None | Constant | No — a feature |
| Excel macros | Low | Runs on command | No — a tool |
| Code assistant | Moderate | Reviews every change | Borderline |
| Customer-service chatbot | High | Handles exceptions | Borderline |
| Autonomous sales agent | Very high | Periodic oversight | Closest to "worker" |
Companies Could Have a New Incentive to Measure AI Labor
This creates an unexpected connection between AI taxation and AI governance.
Organizations are already beginning to ask a set of foundational questions about the AI they use.
Those questions could eventually acquire a financial dimension.
Companies may need to understand not only where AI exists, but also how much economically meaningful activity AI performs.
The AI inventory of the future could therefore contain fields such as:
Today, those fields might sound excessive.
In a highly agentic economy, they may become ordinary corporate records.
The AI inventory of the future may read like a payroll register for machines.
- AI System: Autonomous Customer Service Agent
- Department: Customer Experience
- Owner: VP Customer Experience
- Human Supervisor: Director of Support
- Autonomy Level: High
- Annual AI Cost: $420,000
- Human Employees Supported: 38
- Transactions Completed: 1.8 million
- Estimated Human Hours Supplemented: 42,000
- Risk Classification: Moderate
- Tax Classification: To Be Determined
Every $80,000 salary carries $12,240 of payroll tax
One hypothetical employee at $80,000 · 2026 Social Security and Medicare rates
is performed by technology instead
The Wrong Tax Could Damage American Innovation
There is also a powerful argument against an AI tax.
If the United States taxes AI productivity too aggressively while competing economies encourage adoption, American companies could become less competitive.
AI is likely to become part of national economic infrastructure. Taxing it simply because it makes workers more productive could resemble taxing computers, electricity, or industrial machinery because they reduce the number of workers required for a particular task.
There is another problem.
Companies could move AI workloads across borders far more easily than factories.
A poorly designed AI tax might therefore produce relatively little revenue while encouraging companies to shift infrastructure, intellectual property, or AI operations elsewhere.
The policy objective cannot simply be:
AI replaced workers, therefore tax AI.
It would need to be:
How should the tax system evolve if the relationship between labor, productivity, income and capital fundamentally changes?
That is a much more sophisticated question.
The Bigger Issue May Be Who Receives the Productivity Dividend
The central economic question may ultimately have less to do with whether AI destroys jobs and more to do with where the value created by AI goes.
Imagine AI doubles worker productivity.
If companies keep approximately the same workforce, workers earn more, businesses grow and consumer prices decline, the existing tax system might adapt reasonably well.
But imagine AI doubles productivity while employment falls substantially and most of the economic gain flows into corporate profits and capital ownership.
The tax consequences are entirely different.
Government revenue could increasingly migrate from labor taxation toward taxation of capital, profits, consumption, or automated production.
That could represent one of the largest philosophical shifts in American taxation since the development of the modern income and payroll tax systems.
For generations, public finance has assumed that human employment is one of the principal mechanisms connecting economic production to taxation.
Agentic AI challenges that assumption.
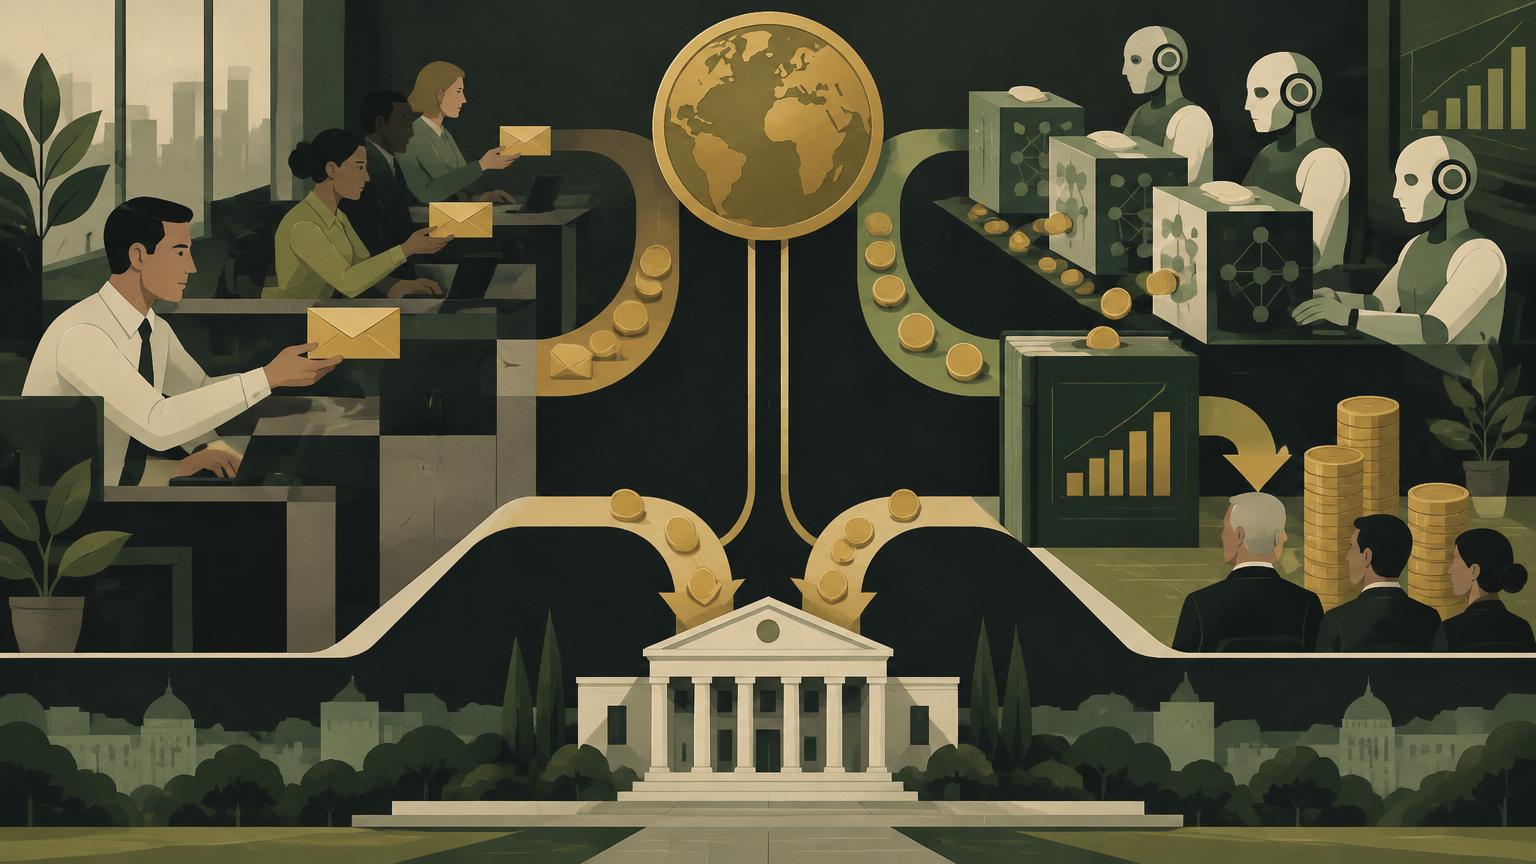
AI Governance Could Eventually Include Tax Governance
This is also why AI governance should not be viewed solely as ethics, privacy, bias, security, and regulatory compliance.
AI governance is ultimately about understanding and controlling how artificial intelligence participates in an organization.
As AI becomes increasingly autonomous, governance programs may need to understand its economic role as well.
Organizations may eventually need to document the economic role of every agent they operate.
An AI governance platform could therefore evolve into something considerably broader than a compliance system.
It could become the organizational record of an enterprise's human and artificial workforce architecture.
- Which agents perform productive work
- Which human functions they supplement — or automate completely
- How much autonomy they possess
- How much economic activity they generate
- What human oversight exists
- Which jurisdiction governs their activity
- And potentially what tax treatment applies
The Tax Debate Has Barely Begun
No one knows whether AI will cause the massive labor displacement that some forecasts anticipate.
History repeatedly demonstrates that technological revolutions can eliminate occupations while simultaneously creating industries, professions, and forms of employment that were previously unimaginable.
AI may follow that pattern.
But agentic AI introduces something historically unusual: scalable cognitive labor that can operate continuously, replicate rapidly, communicate with other machines, and perform increasingly complex economic functions without being a legal employee.
If that capability becomes deeply embedded in American companies, policymakers will eventually have to confront the mismatch between a tax system heavily connected to human labor and an economy increasingly capable of generating value without proportionally increasing human payroll.
The first reaction may be calls to "tax the robots."
That would probably be too simplistic.
The more important debate will concern where economic value originates, who captures it, and how society finances public obligations when human wages represent a smaller share of production.
The eventual answer may be an AI excise tax. It may be an automation adjustment. It may involve corporate profits, capital income, consumption, compute, or some mechanism that has not yet been invented.
It may also turn out that widespread AI augmentation creates enough new occupations and economic activity that the feared revenue gap never materializes.
But governments cannot assume that outcome.
If autonomous AI agents eventually perform a meaningful share of America's economically productive work, the United States will face a fundamental policy question:
Should a tax system designed for an economy of human workers continue taxing primarily the humans, or should some portion of taxation follow the productive capacity that has migrated to machines?
That question reaches far beyond technology.
It touches the future of work, Social Security, Medicare, corporate taxation, economic inequality, competitiveness, and the relationship between citizens, corporations, and government.
AI may therefore force America to rethink more than how people work.
It may force us to reconsider what, exactly, a worker is for purposes of the modern economy and who, or what, should bear the tax burden when productive labor no longer belongs exclusively to human beings.
Sources & further reading
Regulatory requirements depend on the facts and may change. Consult counsel for applicability to your organization.
Understand the AI already working inside your organization
A clear inventory, named owners and documented oversight are useful today—regardless of where the AI tax debate goes next. Explore how GovernIQX supports that foundation.